Let’s look more closely at housing supply in the US and Canada. Housing supply isn’t as flashy as mortgage rates or viral TikToks about “forever renters,” but it’s the slow, structural side of the story that shows up in a patchwork of crowded houses, “no vacancy” signs in resort towns, and the permit line at the local planner’s counter.
The first week of February, we took a broad look at demographic trends around the world, with a closer look at drivers of population change in rural areas. Last week, we discussed housing trends around the world, including broad drivers of the emerging crisis in housing affordability in both developed and emerging nations. This week, we’ll take a closer look at the quantity of new housing in North America and how well the market is meeting the needs of a changing population, from the point of view of planning and public policy.
- The big picture of housing supply and demand
- The rural housing picture
- North American regional housing patterns
Note: I am not an economist, though I work in economic development and passed a finance certification years and years back. I know enough about numbers to know I have to check my statistical analysis twice before I turn in my homework.
The Housing Big Picture: supply vs demand
People need housing. Their ability to find housing they need and like are impacted mostly by two factors–affordability (last week’s focus) and supply. Generally, higher prices should lead to greater supplies… in theory, but life is more complicated than that.
Housing supply in both the US and Canada remains structurally tight overall, but 2024–25 saw some long-awaited catch-up in new construction—especially in the Southern US and in Canada’s larger metros—with notable pockets where supply is now at least keeping pace, and even producing higher vacancies in specific markets and segments.
In the US, estimates of the cumulative housing shortfall cluster around 3.8–4.7 million homes, reflecting years of underbuilding relative to population and job growth. Despite that gap, the website realtor.com reported that 2024 was the first year since 2016 when new-home construction in the US outpaced household formation: about 1.36 million homes were started versus just under one million new households.
Canada has been pushing record-high rental completions, yet rapid population growth has kept conditions tight. Canadian Mortgage Trends News reported last year the national purpose-built rental vacancy rate climbed from a record low 1.5% to 2.2% (2024); other sources report the rate around 3.1% (2025 preliminary reporting), which is still low by historical standards.
US: single-family vs multifamily trends
US home completions rose sharply in 2024, with roughly 178,000 more units finished than in 2023, led by the South; the Northeast had the fewest completions (Statista Research)
In 2024, single‑family construction strengthened while multifamily cooled: single‑family starts reached the second‑highest level since 2007, while multifamily (especially 5+ unit buildings) slowed from the 2021–23 boom. For 2023–24, about two‑thirds of additions to US housing stock were single‑family, a bit more than one‑quarter multifamily, and a small remainder manufactured housing—continuing a long-run pattern but with multifamily still elevated compared with pre‑2010 norms.
As reports for calendar year 2025 come in, we’ll see how the supply vs demand trend is heading. This week, the National Association of Realtors reported sales of previously occupied US homes fell sharply in January 2026, down 8.4% month on month. AP noted “That’s the biggest monthly decline in nearly four years and the slowest annualized sales pace in more than two years. Sales fell 4.4% compared with January last year.”
Where US supply is keeping pace
Places where new construction is roughly matching or beating recent household/job growth tend to feature fast permits and pro‑growth zoning (greenfield land at metro edges, more by‑right approvals).
Some regional patterns show in the data:
- The US South (Texas, parts of Florida, the Carolinas, some Southeast metros) shows the smallest remaining housing supply gap relative to post‑2012 construction and has more for‑sale inventory than in 2017–19 in many metros.
- Realtor.com regional analysis suggests that if 2024 trends continued, the South could erase its supply gap in about three years, versus 6.5 years in the West and decades in the Midwest, while the Northeast’s gap is still widening.
- Some high‑growth Sun Belt metros (Dallas–Fort Worth, parts of Houston, San Antonio, segments of Atlanta’s periphery) are building rapidly, with relatively more single‑family and garden‑/mid‑rise multifamily, which helps keep vacancy rates somewhat higher and prices somewhat more anchored than in constrained coastal markets.
I will dig deeper into these regional trends later in this post.
US shortages remain acute across much of the nation
Coastal and high‑regulation metros—Los Angeles, San Francisco Bay Area, New York, Boston, Seattle, and portions of South Florida—still exhibit severe underproduction relative to job growth and historic demand.
- Los Angeles, for instance, has an underproduction estimated at over 7% of existing units and issues only about one new housing permit for every three new jobs.
These markets skew toward multifamily (often high‑rise or taller mid‑rise) due to land and zoning constraints, but volumes are still below what would be needed to clear backlogs; vacancies are low and prices/rents remain high
Canada: supply trends and where it’s catching up
Canada has seen “record-high rental completions” in 2024, led by purpose-built rentals, as federal and provincial policies have pushed new construction; this is finally beginning to show up in higher vacancies.
The national purpose‑built rental vacancy rate in Canada moved from 1.5% to 2.2% in 2024 and to around 3.1% in 2025 as large cohorts of new units hit the market and population growth cooled modestly. Supply growth is skewed heavily toward multifamily (towers and mid‑rise), especially in Toronto, Vancouver, Calgary, and Montreal; single‑family detached construction is constrained by land prices and municipal zoning.
Canadian markets where supply is keeping pace
Characteristics of Canadian metros where new construction is now roughly matching demand:
- Very high recent completions of purpose‑built rentals (thousands of units per year in some CMAs).
- Strong but not runaway population growth (for example, more balanced inflows of international students and temporary workers).
- More flexible zoning and faster approvals for higher‑density infill.
Media coverage highlights some illustrative patterns:
- Calgary: Purpose‑built rental stock rose at its fastest pace in decades, with roughly an 11% increase in 2025, and vacancy around 5%—suggesting supply is finally out in front of demand, even amid population growth.
- Outer areas of large metros (suburban rings of Toronto and Montreal) are also seeing growing volumes of new rentals and condos, adding slack at the margin even if core-city affordability remains difficult.
Where Vacancies are Rising
In 2024, homeowner vacancy rates in the US were highest in the South (about 1.3%), followed by the West (1.1%), Midwest (0.9%), and Northeast (0.8%), reflecting more building and somewhat more slack in faster‑growing, lower‑cost regions.
Elevated vacancies in certain Sun Belt submarkets (e.g., newly built Class A apartments in fringe locations) often reflect a surge of multifamily deliveries timed into a cooling rent-growth environment, even while affordable segments remain tight. Older rental stock in slower‑growth Midwestern or interior Southern metros often are experiencing higher vacancies, especially in neighborhoods with weaker job or amenity bases, though national averages still point to overall tightness.
In Canada, the national increase to about 3.1% vacancy in 2025 is concentrated in purpose‑built rentals; condo rentals remain tighter. Montreal has seen vacancies rise as non‑permanent residents and international students declined, even while rents climbed sharply—indicating a mix of cyclical demand softening and structural affordability pressure. Calgary’s roughly 5% vacancy rate reflects rapid expansion of new rental supply at mostly higher price points, with demand keeping up enough to prevent a glut but leaving more available units than in Toronto or Vancouver.
Common characteristics of “balanced” vs “unbalanced” markets
Markets where supply growth is at least keeping pace with household formations tend to have:
- Pro‑development policies: easier greenfield development, more permissive zoning for mid‑rise and high‑rise, and more predictable approvals.
- High construction volumes relative to population: elevated single‑family in US Sun Belt metros; elevated purpose‑built rentals in Canadian prairie and some secondary metros.
- Slightly higher vacancies (2–5%) that allow some choice for tenants and buyers, moderating price growth.
Markets with significant shortages and very low vacancy typically show:
- Tight land use controls and lengthy entitlement processes, especially in coastal metros.
- Strong demand drivers: high incomes, job clusters, universities, or immigration hubs.
- Product mix tilted toward expensive multifamily or older stock with limited additions, keeping both rents and prices high despite modest new supply.
A note on Housing Affordability and Housing Demand
It is very trendy now to blame regulatory constraints for the lack of new housing construction. “Zoning Reform” is the call to the gates to win the battle for affordable housing!
Earlier this month, researchers at the Federal Reserve Bank of San Francisco released an “Economic Letter” detailing analysis they have done on housing affordability and housing demand. they point out that prices react to both demand for “quality” as well as “quantity” of housing. Their conclusion: “In this Letter, we argue that differences in the type of underlying labor market growth and subsequent implications for housing demand may offer a better explanation for important housing market dynamics. This suggests that the housing affordability crisis may be best addressed by understanding changes to the labor market, especially the relative distribution of economic growth across income levels and jobs in different areas.”
The Rural Housing Picture
Rural housing in both the US and Canada is under growing pressure: demand has risen sharply since 2020 (remote work, second homes, and workforce needs), while new construction in low‑density areas is still dominated by single‑family homes and is not fully keeping up, especially for year‑round local workers and renters. Keven Park with Fannie Mae noted in late 2024, “Although only a small share of urban residents relocated to rural areas during the pandemic, their influx represented a disproportionate increase in demand for housing in those regions.”
Rural Supply and Demand
Housing supply and demand are trending is similar directions across both nations.
In the US, national builder data shows only about 4-6% of US single-family home permits are in non-metro (including micropolitan) counties. This was still higher than multifamily permit rates, which were down across all US geographies (metro or non-metro), according to reports last year from the National Association of Home Builders (NAHB)
Where rural multifamily is being built in the US, it is usually small garden‑style projects or townhouse clusters in small metro cores and amenity‑rich rural counties (mountain, lake, and outdoor recreation regions). Debra Guerrero, Chair of NAHB’s Multifamily Council, related this week “Elevated construction costs and the local regulatory environment continue to be major headwinds to faster growth. While interest rates have eased slightly, they still need to come down further to significantly spur new construction.”
Canada Mortgage and Housing Corporation (CMHC) analysis indicates rental supply has grown fastest in major centers, but smaller and rural communities lag: most of the 4.1% national rental increase in 2024 came from large CMAs, leaving many small towns and resource regions with very limited new purpose‑built rental stock.
Outside big metros in Canada, new construction is still skewed toward single‑family ownership housing, often on larger lots, while small‑scale multifamily (duplexes, four‑plexes, small walk‑ups) fills most of the rental niche. Because ownership costs have surged, more rural households are seeking rentals, but the stock has not expanded proportionately, contributing to tight conditions and low vacancies even in some places with modest population growth.
Housing Demand Types in Rural Areas
Workforce Housing
Many rural labor markets—agriculture, meatpacking and food processing, mining/energy, tourism services, and healthcare—report shortages of year‑round modestly priced rentals and starter homes, even where overall population growth is flat.
The Up For Growth organization, for example, found that roughly three‑quarters of rural residents agree that there is a housing shortage and that their communities need more homes and rentals, reflecting visible strain on teachers, nurses, farmworkers, and service workers.
In both countries, employers in high‑cost resort/rural economies (mountain towns, coastal fishing/tourism hubs) increasingly sponsor or master‑lease workforce housing, because market‑rate second‑home demand has bid up prices beyond what local wages support.
Remote‑work migration
Fannie Mae research shows mortgage application activity in rural and non‑metro areas rose about 80% after 2020, as urban residents moving to away from cities created a disproportionately large increase in rural demand.
Remote workers often target “rural‑adjacent” or amenity‑rich counties—those near universities, regional hospitals, or attractive landscapes—rather than the most isolated places, supporting higher prices and more new construction in those specific markets. These buyers have been seeking out single‑family detached homes with space and good internet service, which channels demand toward that segment and does little to expand the local rental stock.
Vacation homes and short‑term rentals (STRs)
Recent research by Harvard’s Joint Center for Housing Studies found that home prices in rural vacation areas jumped about 36% between March 2020 and March 2023. This is roughly double the pace in other rural counties, reflecting second‑home and short-term rental (STR) demand in outdoor recreation and scenic regions.
In many US and Canadian resort regions (mountain West, lake districts, coastal villages), a noticeable share of the existing housing stock has shifted into STRs, tightening the long‑term rental supply even when overall unit counts rise. New building in these areas often skews to higher‑end single‑family cabins, chalets, and condo projects catering to seasonal owners and tourists, leaving a gap in year‑round affordable units for local service and tourism workers.
STRs were a major source of neighborhood conflict in my last public sector job in the mountains of Colorado. It doesn’t sound like its gotten any better, with the County Planning Commission recommending legalizing living in RVs since there are no affordable rentals available for working people, an unsafe option especially in the wintertime.
Multifamily demand in rural/small urban markets
NAHB’s indicators show multifamily construction in the US has been strongest in smaller metros and low‑density areas where costs and regulation are lighter, but the overall rural/micropolitan share of multifamily permits remains small and has recently turned negative as financing tightened. Demand for multifamily in rural regions is concentrated among lower‑income households, seniors aging in place, seasonal workers, and young adults forming new households who cannot afford single‑family homes.
In Canada, CMHC data show that virtually all of the significant growth in purpose‑built rentals is still clustered in and around urban centers, so rural and small‑town renters rely heavily on older small multifamily stock, basement suites, or informal rentals, with low vacancy and few new options.
There is some indication more jurisdictions are taking on zoning reform to loosen up single-family zoning, allowing duplex and other house-scale “Missing Middle” homes in residential neighborhoods. More on that later…
A Patchwork Supply and Demand
The pandemic‑era surge of remote‑work, second‑home, and lifestyle migration demand hit many rural markets with very limited, slow‑to‑expand supply, which pushed up prices sharply and strained local‑worker housing. New construction in rural North America has responded primarily through more single‑family building in non‑metro counties, while multifamily production has slowed or remained modest, leaving structural gaps in affordable rentals and workforce housing.
At the same time, there is a growing need for repair and rehabilitation of older rural housing stocks. The Canadian government has invested in retrofits to meet climate policy goals. In the US, pandemic-era federal funding boosted programs like weatherization, and FY2025 appropriations have continued to provide modest funding, yet continued budget pressures put these resources constantly at risk.
The net effect of public and private efforts is a patchwork: some amenity‑rich rural counties now look like “mini‑resort metros” with elevated prices and growing second‑home and STR shares, while many other rural regions still struggle with aging stock, low construction volumes, and shortages of decent, affordable multifamily and workforce units for permanent residents.
Patterns in North American Rural Housing Markets
Rural housing across North America is being pulled in two directions at once. On one side, amenity‑rich small towns, rural‑adjacent counties, and resource or service hubs are seeing renewed demand from remote workers, retirees, and in‑migrants in search of relative affordability. On the other, long‑standing structural gaps—aging stock, thin rental markets, manufactured homes past their prime, and scarce new construction outside a few hot corridors—leave many communities short of safe, attainable homes for the people who already live and work there.
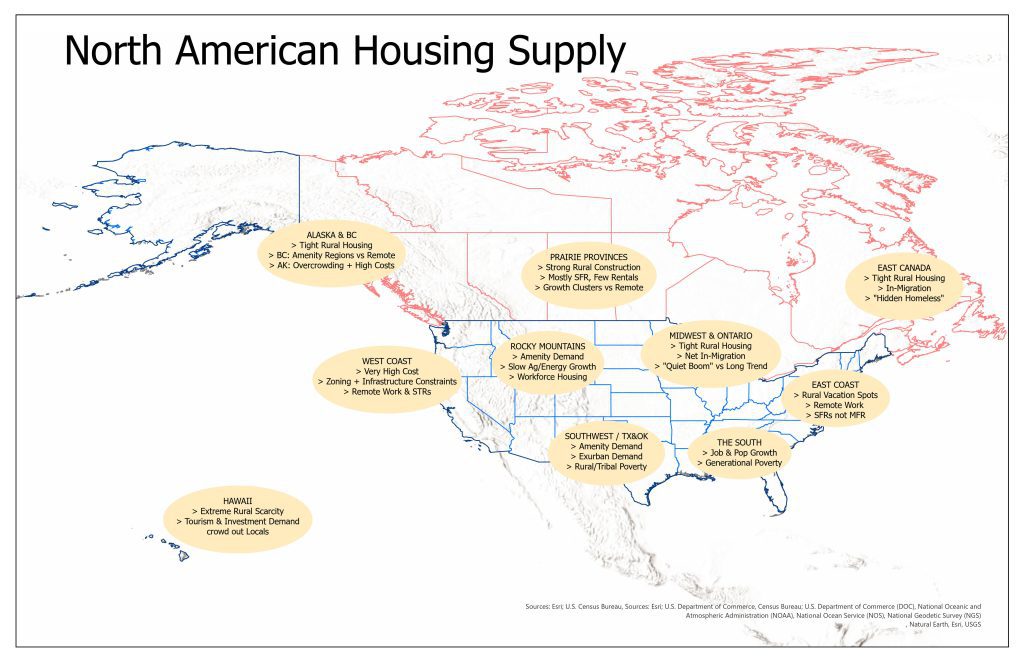
This section looks at how those tensions are playing out region by region, and what today’s patterns might tell us about the next decade of rural housing. Let’s look at some of the common patterns in rural housing markets across different regions of the US and Canada.
Midwestern US and Ontario
We’ll start where I come from—the rural Midwest. Rural parts of the Midwestern states and the Province of Ontario are both seeing structurally tight housing for locals, modest but uneven new construction, and a growing split between “quietly booming” amenity/commuter towns and stagnant, aging‑stock communities. Both US and Canadian analysts project long-term large housing gaps across both nations as housing supply and affordability continue to diverge.
Rural Midwest: supply, demand, and trajectory
New construction in much of the rural Midwest has been unusually weak for more than a decade; research from the University of Illinois notes that Midwestern communities have some of the lowest new housing unit counts per 10,000 residents in the country, leaving aging stock and limited options. Here in Nebraska, for example, many communities across the state (urban and rural) face a critically tight housing supply (typically only a one- to two-month inventory of homes for sale).
Since 2020, rural population growth is being sustained almost entirely by net in‑migration (people moving in, not more births), which includes remote workers and return migrants, adding demand without a corresponding building boom. Analysis by Fannie Mae finds that mortgage demand increased across all types of rural communities after 2020, with institution‑rich hubs (near universities, hospitals, diverse economies) seeing sustained elevated demand.
Patterns today
- Workforce housing shortages: Many small Midwestern towns with meatpacking, agriculture, light manufacturing, or regional medical centers report too few decent rentals or starter homes for workers, even where population growth is modest. The City of Burwell, Nebraska, for example invested Nebraska Affordable Housing Trust Fund financing with local match to build two new workforce homes last year. It’s a drop in the proverbial bucket, but it’s a start. The Aurora, Nebraska, Housing Development Corp. assembled a combination of Nebraska Rural Workforce Housing, Nebraska Investment Finance Authority, and local match funds to capitalize a revolving loan fund for rural workforce housing
- Remote‑work spillover: “Donut effect” dynamics mean some remote workers are moving from core cities into lower‑density counties around metros like Des Moines, Iowa; Omaha, Nebraska; Kansas City, Missouri/Kansas; Columbus, Ohio; and smaller regional hubs, tightening those fringe/rural‑adjacent markets.
- Product mix: New building that does occur is heavily single‑family, often on the edges of small cities or in attractive lake/woodland counties; small house-scale multifamily (duplexes, 4‑plexes) is underbuilt relative to renter demand. The Aurora Housing Development Corp. invested in both single family and townhome lots for new construction.
Likely future trajectory (Midwest)
Without policy changes, many rural and micropolitan Midwestern areas will continue to have:
- Slow but positive net in‑migration.
- Low but gradually rising home prices.
- Persistent shortages of modern, energy‑efficient workforce and senior housing.
Amenity‑rich or institution‑rich communities (college towns, health‑care hubs, lake districts) are likely to see above‑average demand from remote workers and retirees, pushing prices higher and justifying more single‑family and small multifamily projects. Older, depopulating rural counties, on the other hand, will likely keep struggling with very low construction, high repair needs, and functional shortages (few livable units even when nominal vacancies exist).
Rural and small‑town Ontario: supply, demand, and trajectory
- Ontario has explicit provincial housing targets but is not yet hitting them: 73,617 housing starts and 94,908 new homes in 2024, about 76% of the 125,000‑home target.
- Most of those starts are in or near large Census Metropolitan Areas (CMAs), so smaller cities and rural areas are absorbing spillover demand from Toronto and Hamilton but without commensurate new construction.
- CMHC’s recent supply work shows that ground‑oriented construction (single‑detached, semis, townhomes) has grown modestly in more affordable markets, with developers and buyers increasingly looking to secondary centers and small communities.
Patterns today
- Spillover from the Greater Toronto Area (GTA): Towns and rural municipalities in Southwestern and Central Ontario (e.g., Brantford/Brant County and similar communities) are seeing buyers priced out of Toronto and Hamilton seeking more attainable ownership, especially ground‑oriented homes.
- Limited purpose‑built rentals: Smaller Ontario markets still lean heavily on single‑family and informal rentals; purpose‑built rental and multifamily construction is heavily concentrated in larger centers, leaving rural renters with older and thinner stock.
- Affordability pressure: Even where prices remain lower than the GTA, higher rates and incomes that have not kept pace with housing costs mean many local workers in rural/small‑town Ontario face tight budgets and a scarcity of modest rentals.
Likely future trajectory (Ontario)
As long as big‑city affordability remains strained, demand will keep pushing outward into small cities and exurban/rural townships within commuting or partial‑commuting distance, especially along good highway or rail corridors.
Provincial and municipal moves to support more “gentle density” (secondary suites, lane houses, row housing) will gradually increase small‑scale multifamily and rental options, but the impact will be incremental and highly uneven across municipalities. In more distant rural areas (far Northern Ontario, remote agricultural or resource regions), low incomes and high construction costs will continue to limit new building, leaving aging, often inadequate stock despite nominal vacancies.
Shared themes: Midwest vs Ontario rural
Demand drivers: Both regions are seeing:
- Remote‑work and lifestyle migrants targeting affordable, high‑amenity small towns.
- Local workforce housing needs outpacing new local construction.
- Aging populations needing accessible, smaller homes and rentals.
Supply mix: New supply skews toward single‑family ground‑oriented housing; purpose‑built rentals and multifamily are growing from a low base and mostly in larger nearby centers, not the most rural places.
Trajectory: Absent aggressive policy or major economic shocks, expect gradual tightening in attractive rural‑adjacent and small‑city markets (higher prices, moderate building) and chronic under‑investment plus aging stock in more remote communities.
Rural Northeastern US and Eastern Canada
Rural housing in the Northeastern US and Eastern Canada is being reshaped by similar forces—remote work, amenity migration, and long‑standing structural shortages—but the balance between demand and new building is generally tighter on the Canadian side, with more pronounced supply gaps and slower construction relative to population growth.
Demand: who is moving where?
- In the Northeastern US, rural and non‑metro counties saw a sharp reversal from pre‑2020 decline to significant net in‑migration, with typical home prices in non‑metro Northeast counties up about 40.5% between March 2020 and March 2023.
- Fannie Mae notes that mortgage application activity in US rural and non‑metro areas jumped roughly 80% above pre‑pandemic norms and remains elevated into 2024, driven by second‑home buyers, remote workers, and other in‑migrants.
- In Eastern Canada (Atlantic provinces plus rural parts of Quebec and eastern Ontario), remote work has also enabled movement from big cities to smaller centers, but overall housing demand has outstripped supply nationally: CMHC estimates Canada needs up to 4.8 million additional homes over 10 years to restore 2019‑level affordability.
Patterns of rural demand
Rural areas of the Northeastern US are experiencing:
- Strong demand in high‑amenity, rural‑adjacent counties (Vermont, New Hampshire, Maine, the Catskills/Hudson Valley, coastal New England), largely from higher‑income, remote‑capable households leaving Boston/NYC metros.
- Distressed demand in Appalachian and interior counties (e.g., parts of NY, PA, WV) where incomes are low and households primarily seek safe, basic housing rather than lifestyle acreage.
In rural Eastern Canada:
- In Atlantic Canada, inflows from Ontario/Quebec and from international immigration have pushed up demand in small cities and rural areas once seen as “cheap backwaters.”
- Rural Nova Scotia, New Brunswick, and PEI report intensified pressure on rentals and starter homes as remote workers and retirees arrive, while many local households already faced affordability problems.
Supply: what is being built (and where)?
- In the US Northeast, new rural construction is still dominated by single‑family homes, often higher‑end or second‑home suitable; missing‑middle rentals and small multifamily remain scarce in most rural towns.
- Many distressed Appalachian counties face large needs for repair and replacement rather than large new‑build booms; assessments in Central Appalachia and Appalachian Ohio (straddling the Midwest and Eastern US) highlight aging stock with incomplete plumbing, poor energy performance, and limited new construction.
- In Eastern Canada, the national supply response is lagging more visibly: CMHC and provincial analyses stress that construction must roughly double in several provinces to keep up with demand.
Examples:
- Nova Scotia: CBC has reported on CMHC estimates that housing starts need to rise from about 5,400 per year to over 12,500 annually between 2025 and 2035 to restore pre‑pandemic affordability, with needs “across the spectrum” (rental and ownership, all types).
- A Nova Scotia housing needs summary identifies a roughly 27,300‑unit gap between demand and available supply across the province as of 2022, including rural areas.
- Rural Nova Scotia’s “affordable housing crisis” has been flagged for years, as the CBC has noted: many rural tenants struggle with hidden homelessness, poor‑quality housing, and very limited new affordable units
Rural Prairie Provinces of Canada
The Prairie Provinces (Alberta, Saskatchewan, Manitoba) currently have some of the strongest housing‑construction momentum in Canada and more balanced conditions than Ontario or B.C., but they are not immune to the national shortfall and still face tight markets in key cities. Urban centers in the Prairie Provinces (Calgary, Edmonton, Winnipeg, Regina, Saskatoon) are seeing high construction and rising vacancies in some segments, while many rural and small‑town areas remain tighter with slower building and more limited product variety.
Rural and small‑town Prairies: slower supply, more constraints
- Federal 2025 investment snapshots note roughly 10,000 homes funded across Prairie communities, but most of the largest projects are in or near urban centers; smaller communities receive fewer, smaller‑scale builds.
- Rural municipalities remain dominated by single‑detached construction, including acreages and small‑town subdivisions; higher‑density formats (townhomes, small multifamily) are growing but still limited compared with urban areas.
- In many rural areas, nominal vacancies coexist with functional shortages because a sizable share of stock is older, in need of repair, or poorly located relative to current jobs and services.
Rural demand profile
Key rural demand drivers in the Prairies include:
- Workforce housing for agriculture, energy, logistics, and resource‑sector workers.
- Some remote‑work and lifestyle migrants seeking more space and lower prices, especially near lakes or along corridors into major cities.
Unlike the big cities and similar to much of the rest of small town US and Canada, rural areas in mid-Canada are seeing little purpose‑built rental construction; renters rely on older houses, small plexes, and informal suites, so even modest population growth can strain supply. Transit and infrastructure investments are also thinner in these areas, so demand often concentrates in rural‑adjacent zones within realistic commuting distance of Calgary, Edmonton, Winnipeg, Regina, or Saskatoon, leaving more remote places with stagnant or declining demand.
What makes the Prairies different from the rest of Canada?
Supply dynamics
- Housing starts and completions are growing faster in the Prairies than in most other provinces, driven by both single‑detached homes and purpose‑built rentals in key cities.
- A 2025 analysis observed that new units in the Prairies and Quebec tend to be larger and more “livable” than the small condo micro‑units common in Toronto and Vancouver, making them better aligned with resident demand rather than speculative investors.
- Home‑builder sentiment in the Prairies sits around neutral (index near 49), versus notably weaker multi‑family sentiment nationally, suggesting builders there still see enough demand to justify projects but are cautious.
Demand dynamics
- Alberta and Saskatchewan have seen strong interprovincial in‑migration from Ontario and B.C., attracted by lower prices and solid job growth, which has kept sales near record levels and inventories near 20‑year lows.
- TD Economics’ provincial outlook describes Saskatchewan and Manitoba as among the “hottest” markets in 2025, with Saskatchewan’s average home price up about 9% year‑over‑year on solid affordability and firm job growth.
- Alberta’s market is more balanced than in 2023–24 because listings have risen faster—helped by a “massive ramp‑up” in completions—so price growth has been softer than in its Prairie neighbors despite strong inflows.
Likely trajectories
It seems likely for areas of the Prairie Provinces outside the larger metro areas to expect modest, targeted growth in higher‑density formats (townhomes, small multi‑unit) in rural‑adjacent communities and along strong commuter corridors, driven by affordability‑seeking households. Continued above‑average construction, especially of larger single‑detached and purpose‑built rentals, should keep markets closer to balance and prevent extreme shortages seen in Ontario and B.C.
Ongoing workforce‑housing pressure will remain in resource and agricultural hubs, where employers may increasingly partner on housing or push for supportive local policies to add stock. Many more remote communities will likely remain in a low‑construction, aging‑stock equilibrium, where the central challenge is not just unit count but quality, rehabilitation, and matching housing to evolving labor and demographic patterns.
In map terms, you can think of the Prairies and Quebec as Canada’s current “production frontiers,” adding a lot of units and attracting migrants, while Ontario and B.C. remain demand magnets with chronic under‑supply
British Columbia and Alaska
On the northern Pacific Coast, rural housing in British Columbia and Alaska are both under heavy strain, but for different reasons: BC’s rural areas are squeezed by the same supply shortage and price pressures hitting its cities, while rural Alaska faces an extreme shortage of basic, safe housing, with very high overcrowding and construction costs.
British Columbia: rural pressure from growth and policy catch‑up
BC as a whole is deeply underbuilt; one major estimate says the province needs over 450,000 additional homes by 2030 to get back to early‑2000s affordability. Provincial policy now explicitly recognizes that rural and small‑town communities are also in crisis: the province notes “rural communities across the nation are feeling the pressure” and is funding new projects in Interior and northern BC.
Many rural and small‑town areas (Interior, Kootenays, north, Island outside Victoria) saw in‑migration during and after the pandemic from larger BC cities and other provinces, as people sought lower prices and outdoor amenities. That added demand to limited local stock.
Local workforces (health care, resource industries, tourism, small manufacturing) report difficulty hiring because workers cannot find suitable rentals or modest ownership homes near jobs. In some rural districts, housing‑needs reports show a significant share of households in low or very low income brackets and a projected need for both ownership and affordable rentals through 2041.
Rural supply and policy response in BC
BC Housing and the province are funding rural and small‑town projects mainly through the Community Housing Fund; one 2024 intake selected 15 projects in Interior and northern BC totaling 584 affordable rental homes across multiple communities.
The province’s Homes for People plan and Housing Supply Act set housing targets for dozens of municipalities; some smaller centers are included, with explicit guidance on how many units should be rental, below‑market, or supportive.
Critically for rural and small communities, BC’s 2023–24 zoning reforms require “small‑scale multi‑unit” housing (duplexes, triplexes, townhouses) to be allowed on most residential lots, and nearly 90% of communities have adopted these changes into their bylaws.
Where BC rural trendlines are headed
Demand: Likely to remain firm in amenity‑rich areas (Okanagan, Kootenays, coastal and Island towns) and in resource/service hubs, especially if remote/hybrid work stays common.
Supply: Provincial targets and blanket missing‑middle zoning should gradually increase small‑scale multi‑unit and rental options in many rural centers, but actual delivery will depend on local capacity and builder interest; labor and cost constraints mean the province may still fall short of its overall housing goals.
Net result: Rural BC probably stays tight, with some easing over time where public/non‑profit projects and new small‑scale multi‑unit infill come together; poorer or more remote areas will see slower change and continued shortfalls in affordable units.
Alaska: extreme overcrowding and slow, high‑cost building
Alaska’s rural housing crisis is more severe than in most of the continental US or BC: overcrowding in rural Alaska Native villages is about four times the national average, with over 44% of households severely overcrowded.
A recent Alaska Safe Housing Assessment describes Alaska’s housing crisis as “worse than in the rest of the United States,” highlighting overcrowding, high costs, limited services, and lack of coordinated planning, especially in remote villages.
Rural demand patterns in Alaska
Demand in rural Alaska is driven primarily by basic need—safe, uncrowded, structurally sound housing—rather than amenity‑seeking migrants or second‑home buyers in most remote areas. Overcrowding, domestic‑violence risks, and limited shelter options force survivors to choose between staying with an abuser or becoming homeless; this creates intense demand for any additional, safe units.
In some regional hubs and resource‑towns there is also workforce housing pressure, but in far‑flung villages the main issue is the sheer lack of adequate dwellings and the deterioration of existing stock.
Rural supply realities in Alaska
Construction in remote communities is extremely expensive and slow. The Alaska Safe Housing Assessment Report cites a project where an organization spent $100,000 just in transportation costs to bring in materials to construct one building in a rural community.
In many rural regions, the responsibility for new housing falls largely on regional housing authorities with limited funding; high costs, remoteness, and lack of basic infrastructure (roads, water/sewer, energy) all impede building. Overcrowding metrics are stark: earlier assessments showed that in the Bering Straits region 37% of homes were overcrowded, and in Savoonga about 61% of homes met HUD’s overcrowding definition.
Where Alaska rural trendlines are headed
Without significantly higher and more stable federal and state investment, rural Alaska will likely continue to experience severe overcrowding and slow net additions to the housing stock.
The focus will remain on small numbers of new units and on rehab, weatherization, and making existing homes safer, especially for Alaska Native women and families facing violence; large greenfield developments are unlikely in many villages because infrastructure and costs are prohibitive. Climate change (permafrost thaw, erosion, storms) will likely force replacement or relocation of housing in some communities, adding to already high needs and costs.
West Coast
Rural West Coast housing (in California, Oregon, Washington, plus rural Hawaii) is unusually strained: cost burdens are the highest of any US region, demand is being reshaped by remote work, tourism, and second‑home buyers, and new supply is not keeping up in most high‑amenity rural areas.
Big picture: rural West Coast vs other regions
Rural households in the Western US have the highest housing cost‑burden rates nationally: roughly 28.9% of rural Western households are cost‑burdened, with rural California at 37.4%, Hawaii at 34.1%, Washington at 30.4%, and Oregon at 29.6%. Across the rural Pacific West (coastal counties, Sierra foothills, and rural Hawaii), high cost burden stems from limited developable land, strong amenity/tourism demand, and regulatory limits on new housing, particularly multifamily.
California, Oregon and Washington
Demand Drivers
- Remote work has shifted demand toward more affordable and scenic areas away from the largest metros; in California, suburban and rural regions like parts of Sonoma County, the Central Coast, and interior counties have seen stronger interest as remote workers prioritize space and quality of life over proximity to downtowns.
- Many rural‑adjacent counties (e.g., Sierra Nevada foothills, North Coast, inland valleys in CA; Willamette Valley fringes and southern Oregon; interior Washington valleys) attract both retirees and households priced out of metros, adding to local demand for single‑family homes.
- Tourism and amenities (wine regions, redwood coast, coastal Oregon towns, Columbia Gorge, mountain lakes) support demand for vacation homes and short‑term rentals, tightening year‑round rental supply.
Supply and unit types
- New rural construction is dominated by single‑family homes on larger lots; multi‑unit development (small apartments, townhomes) is rarer due to zoning, infrastructure limitations, and local opposition.
- Some smaller cities and “hidden‑gem” markets (e.g., Central Point, OR, Ridgecrest, CA) still have relatively lower home values than their states’ averages, but these remain exceptions in a generally high‑cost region.
- In many rural counties, the existing stock is older and not easily adapted to current demand (e.g., needs for home offices, energy efficiency, and good broadband), which increases pressure on the limited pool of updated homes.
Rural West Coast trajectories
Remote work is likely to keep a floor under demand for rural and small‑town areas, especially within a few hours of major metros. As long as the back-to-the-office movement stays chill, remote work and entrepreneurial spirit would support continued price pressure on single‑family homes even if overall statewide markets cool.
That said, without some level of zoning reform and significant infrastructure investment, most rural West Coast areas will see only incremental infill and scattered single‑family construction rather than large‑scale, diversified new supply, leaving rental options tight and cost burdens elevated.
Hawaii’s rural areas: an extreme version
Current conditions
- Hawaii’s housing shortage is severe statewide, and rural areas (especially Hawaiʻi Island, Maui, and Kauaʻi counties) face some of the sharpest constraints: The Hawai’I Housing Planning Study reported only about 4.1% of housing units were vacant and available for residents in 2022.
- Around 9.1% of Hawaii’s housing units are used for seasonal or vacation purposes, with Kauaʻi’s share at roughly 11.6%, significantly reducing housing available for full‑time residents.
- The 2024 housing planning study estimates a need for about 64,490 additional housing units by 2027, with a large share required for very low‑income households; only about 13,471 units are currently in the development pipeline.
Rural demand specifics
- Rural and neighbor‑island areas experience high demand from tourism, second homes, and investment properties, which channels development toward resort and vacation product rather than local workforce housing.
- A significant portion of needed new units is for homeownership, particularly single‑family homes on Hawaiʻi Island, where over half of eligible Department of Hawaiian Home Lands households express a strong preference for single‑family ownership.
- Workforce shortages in tourism, healthcare, and public services are tied directly to housing scarcity, as workers face overcrowding, long commutes, or relocation off‑island.
Rural Hawaii trajectories
Given regulatory limits on multifamily, scarce land, and high construction costs, rural/neighbor‑island Hawaii is likely to continue experiencing severe undersupply, especially of affordable rentals, unless there is substantial policy change or subsidy.
Even if some additional multifamily and workforce projects move forward, strong second‑home and vacation‑rental demand will keep rural Hawaii structurally tight, with ongoing out‑migration of lower‑income residents and heightened cost burdens.
What this suggests for the next 5–10 years
Rural West Coast states, including Hawaii, are likely to remain among the most expensive rural housing markets in the US, with cost burdens sustained by strong amenity, remote‑work, and tourism demand and constrained multifamily supply. The most acute problems will persist in high‑amenity zones (coastal towns, wine regions, mountain and lake areas, and Hawaii’s neighbor islands), where vacation and second‑home uses compete directly with local workforce needs.
Policy tools—short‑term rental regulations, incentives or requirements for workforce housing in resort projects, zoning changes for small‑scale multifamily, and targeted subsidies—will largely determine whether rural communities can add enough year‑round, moderately priced housing to stabilize local populations.
Rural Rocky Mountain States
Rural housing in the Rocky Mountain states is bifurcated: amenity‑rich resort and “mountain‑valley” communities face chronic shortages and very high prices, while more remote or less scenic rural areas often have stagnant construction, aging stock, and weaker—but still constrained—options for local workers.
There are basically two core patterns to rural housing in the Rockies, similar to the patterns we see in several other regions:
- In high‑amenity counties (ski areas, national‑park gateways, river and trail hubs), demand from second‑home owners, short‑term rentals, and remote workers far exceeds the growth of year‑round workforce housing.
- In more agricultural or energy‑oriented rural counties, population growth is slower, but there are still shortages of decent, affordable units for workers because the stock is old, scattered, and expensive to replace.
Demand drivers
- Tourism and recreation: Resort counties in Colorado, Utah, Montana, Wyoming, and Idaho (e.g., Summit, Eagle, Pitkin, and Routt counties in Colorado; Bozeman and Whitefish in Montana; Jackson in Wyoming; Moab in Utah) draw heavy demand from visitors and second‑home owners; many homes sit partly vacant or in short‑term rental pools rather than serving full‑time residents. My old friends in Pagosa Springs (Archuleta County) have joined this gang.
- Remote‑work migration: Since 2020, a wave of “work from anywhere” households has bought or rented in mountain towns within a half‑day’s drive of major metros (e.g., from Denver into the Rockies), absorbing limited inventory and bidding up prices.
- Workforce housing: Employers in tourism hubs report that lack of housing for service workers (hospitality, teachers, healthcare, public works) is now a primary operational constraint; some businesses struggle to remain open year‑round because staff cannot find local housing.
Supply patterns and unit types
New construction in rural Rocky Mountain resort counties skews heavily to higher‑end single‑family homes and condos aimed at wealthier households and investors; true workforce and year‑round rental projects are smaller in number.
In many mountain towns, the rise of short‑term rentals has converted a notable share of housing from year‑round occupancy to vacation use, tightening long‑term rental supply even where total units have grown. Limited land, high construction costs, infrastructure constraints, and community resistance to density all restrict large‑scale multifamily development; where it does appear (e.g., small apartment complexes or motel‑to‑housing conversions), demand vastly exceeds available units.
Colorado mountain counties
Surveys of residents in the west slope communities of Eagle, Grand, Pitkin, Routt, and Summit counties in Colorado show that roughly half of homes are occupied by full‑time residents, with the remainder second homes or part‑time use; locals rank affordable and workforce housing as “severe problems.” Analyses of Colorado mountain affordability find that five of seven high‑country resort counties have severe housing shortages, with only a couple showing slight surpluses; even there, shortages are acute at workforce price points.
Several communities are experimenting with:
- Lodging‑tax surcharges dedicated to workforce housing and childcare.
- Deed‑restricted units reserved for local workers.
- Public–private partnerships and motel conversions (e.g., Durango’s Residences at Durango project which converted an old Best Western on US 160) to expand low‑income housing.
Idaho, Montana, Wyoming, Utah “northern tier”
A regional study by Professor Arthur C. Nelson, FAICP, published in The Western Planner, examined the “Northern Tier” (Idaho, Montana, Wyoming, and the Dakotas) indicates large unmet housing needs concentrated in fast‑growing amenity regions; Idaho alone accounts for about 40% of projected needed new units, with Montana around one‑quarter and Wyoming roughly 13%.
In Montana, short‑term rentals and second‑home demand in places like Whitefish, Bozeman, West Yellowstone, and Kalispell have shifted housing away from year‑round residents and constrained rental availability. Bozeman is my favorite place anywhere, but even 25 years ago we couldn’t afford to live there on a public planner’s salary.
Similar patterns appear in gateway communities such as Jackson Hole, Wyoming, and Moab, Utah: strong tourism and in‑migration, very limited workforce housing, and growing policy debates over caps or regulations on short‑term rentals.
How rural Rockies differ from “ordinary” rural America
Unlike many Midwestern or interior rural regions where demand is lukewarm and prices modest, Rocky Mountain recreation counties combine small housing bases with global demand, producing metro‑level or higher prices on rural incomes. Even when nominal vacancies exist in older or fringe units, functional vacancies (places that are actually habitable, affordable, and near jobs) are extremely low, especially for renters.
Remote or non‑amenity rural counties within the same states may see flat or even declining demand, aging stock, and limited investor interest, creating a patchwork where some counties are overheated while neighbors remain under‑invested.
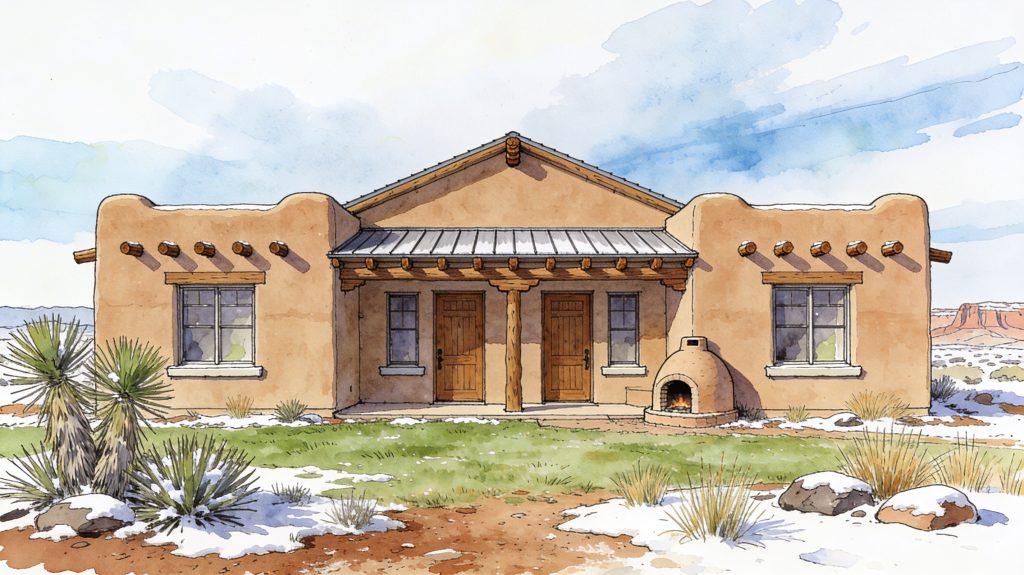
The Southwest
In the rural Southwest (especially Arizona, New Mexico, Nevada, and parts of Utah), you see two overlapping stories: amenity and tourism‑driven hot spots with tight markets and rising costs, and Native/tribal and low‑income rural areas with severe under‑supply, overcrowding, and very slow new construction.
Remote‑work and lifestyle migrants are adding demand in rural‑adjacent and amenity areas—places within reach of Phoenix, Tucson, Albuquerque, Las Vegas, and smaller metros, often with scenery or historic character. Second homes and short‑term rentals (STRs) are important in tourist regions such as northern Arizona (Sedona, Flagstaff corridor), parts of New Mexico (Taos, Ruidoso, Santa Fe periphery), and recreation areas in Utah and Nevada; they divert a slice of stock away from year‑round residents.
In contrast, tribal and very rural communities—especially on the Navajo Nation and other reservations—face long‑standing shortages, overcrowding, and inadequate infrastructure, with demand driven by basic habitability and family formation rather than in‑migration or tourism.
Supply and unit types in rural Southwest
New construction outside metros is still overwhelmingly single‑family detached: subdivisions near small towns, scattered lots, and manufactured homes; small multifamily appears mainly around regional job centers and in a few workforce projects.
STR growth has been rapid in Arizona: Axios reports there were about 50,000 active Airbnb/Vrbo listings statewide by 2024, up from roughly 30,000 in 2019, with heavy concentration in more urban tourist markets like Scottsdale, Sedona, and central Phoenix—but affecting rural communities as well.
Tribal and very rural communities
On the Navajo Nation, past needs assessments indicate tens of thousands of units needed both to replace substandard homes and to relieve overcrowding; more recent plans include only dozens of new units at a time, underscoring how slow the supply response is relative to need. The Navajo Nation has an overcrowding rate close to 39%, versus around 6% nationally, with many homes lacking complete plumbing or kitchen facilities.
A 2025 Navajo Housing Authority plan calls for projects such as 20 new rentals in Pinehill, New Mexico and 60 in Window Rock, Arizona, plus a broader initiative to triple annual homebuilding to roughly 36–40 homes per year—still tiny compared with the massive number of units needed.
Even where population growth is slow or flat, deterioration and overcrowding mean effective demand for replacement and additional units remains high.
Rural housing demand types
1. Remote‑work and “rural‑adjacent” demand
- Arizona, Utah, and to a lesser extent New Mexico are now significant remote‑work destinations; they show up among states with high interest in work‑from‑home jobs, and state programs like Utah’s Rural Online Initiative explicitly try to tie remote work to rural communities.
- Some exurban and small‑town communities (e.g., Maricopa and similar Arizona towns; rural bedroom communities near metro Albuquerque) are marketing themselves to remote workers with new master‑planned subdivisions, fiber internet, and builder incentives.
- This demand is mostly for newer single‑family homes with space for a home office; it rarely adds much dedicated rental stock, so it can tighten markets for local renters if it competes for the same inventory.
2. Vacation homes and short‑term rentals
- In Arizona’s tourist nodes, STR growth has been large enough to be considered a contributor to the housing shortage, concentrated in tourist destinations.
- Arizona has debated bills to allow more “casitas” (ADUs) and missing‑middle housing on single‑family lots; local governments worry some of that new stock will also become STRs, limiting benefits for workforce housing.
- New Mexico allows STRs in many residential and agricultural zones with permits, which formalizes but also potentially expands lodging use in places like Santa Fe and Taos, where local workers already struggle to compete.
3. Workforce and employer‑linked housing
- Employers in remote‑work‑adjacent rural hubs (data centers, logistics, healthcare, energy, outdoor recreation) increasingly report that lack of housing is a constraint; some turn to temporary “remote work housing” solutions or seek public–private partnerships to build rental units.
- The Navajo Nation is seeing investments aim simultaneously at building homes and creating construction jobs—such as the SWIF project, a new training facility at Gallup, New Mexico, which promises to triple local homebuilding capacity and deliver 60 homes for veterans plus additional units over several years.
- Workforce housing needs also intersect with climate and infrastructure; in some colonias‑type and unincorporated areas of New Mexico and Arizona, basic water, sewer, and roads are still limiting factors for both existing and new housing. Yes, basic safe water and utilities are still a thing in many rural areas of the Western US.
Local rural housing patterns
Northern Arizona and similar amenity zones
- Sedona, Flagstaff‑area communities, and other northern Arizona towns combine tourism, STR demand, and remote‑work interest; local stakeholders describe disappearing year‑round neighbors and homes converted into “quasi‑hotels.”
- Supply response tends to favor high‑end homes and STR‑friendly properties; missing‑middle and workforce projects are limited without subsidies or aggressive zoning changes.
- Over the next 5–10 years, continued amenity demand plus ADU/middle‑housing reforms could add units, but without strong STR regulation and targeted workforce programs, much of that new space risks being absorbed by vacation and remote‑work uses.
Rural New Mexico, including tribal areas
- Many small New Mexico towns have flat or modest population growth but significant under‑investment in housing; much of the stock is older manufactured homes or self‑built housing, often in need of rehab.
- STRs are growing in tourism‑oriented pockets like Taos and Ruidoso; statewide rules allow them widely, so local regulation becomes the main tool to protect long‑term rentals.
- On and around the Navajo Nation and Pueblos, the main trajectory is gradual expansion of small rental projects and self‑help ownership programs, but at a pace far below underlying need unless federal and tribal funding is scaled up substantially.
Rural Nevada and Southern Utah
- In Nevada, most rural housing pressure is linked to specific projects (mining, energy, logistics) and to spillovers from Las Vegas, Reno, and recreation areas; small towns can swing from slack to tight when a major employer arrives because rental stock is thin.
- Utah has leaned into rural remote work (state programs and job portals for rural jobs), which can support small‑town housing demand along main corridors; however, actual construction still skews to single‑family, with very limited multifamily in most rural counties.
- Over the next decade, expect a patchwork: certain corridor towns and recreation hubs will see continued in‑migration and rising prices, while more isolated places may struggle to justify new construction and focus on maintaining or replacing aging stock
Likely 5–10‑year trajectories
Amenity and rural‑adjacent hotspots (northern AZ, parts of NM, corridor towns in UT/NV)
- Persistent demand from retirees, remote workers, and regional migrants, with prices likely to outpace local incomes absent strong building and regulations.
- Incremental expansion of single‑family subdivisions, ADUs, and some small multifamily, but with a constant tension between STR/second‑home uses and year‑round housing.
- More local experimentation with STR caps, STR‑specific taxes, and linkage fees or incentives for workforce housing.
Tribal and very rural communities
- Structural shortages and overcrowding remain the central challenge; even aggressive local efforts to triple homebuilding translate into only dozens of new homes per year.
- Housing trajectories hinge on federal and state funding, infrastructure upgrades, and the ability to train and retain local construction workforce.
- Out‑migration toward regional hubs will continue for some households, but attachment to ancestral lands and cultural factors mean many will stay even in crowded or substandard housing unless options expand.
Cross‑cutting theme
Across the rural Southwest, the main pattern is not excess vacant housing but a mismatch: plenty of buyer and STR demand for scenic and remote‑work‑friendly properties, and deep unmet need for safe, affordable, year‑round housing for local workers and tribal communities, with very different price points and policy tools relevant to each.
Texas and Oklahoma—a bridge between the South and Southwest
Texas and Oklahoma’s rural housing markets sit between two models: to the west, more strongly “amenity/remote‑work” and tribal‑shortage dynamics (Southwest); to the east, more entrenched poverty/aging‑stock problems (rural South and Appalachia). Both states mix elements of each, but with relatively stronger growth pressures in specific corridors and relatively weak construction in many truly rural counties.
Compared with rural areas to the east across the Deep South, Texas and Oklahoma have somewhat stronger economic growth and in‑migration in key regions, but they share problems of aging stock, single‑family‑heavy zoning, and shortages of small, affordable units and rentals.
Compared with rural areas to the west (New Mexico, Arizona, mountain West), they see less extreme second‑home/STR pressure in most places, but energy, logistics, and manufacturing projects create sharp local workforce demands, particularly in the Permian Basin and Panhandle.
Both states are central to the broader “rural renaissance” narrative—hidden‑growth markets drawing investment and remote workers—yet much of the actual new construction is concentrated in or near metros, not the most rural counties.
Rural Oklahoma: slow building, big workforce‑housing gaps
- Analysis of the 2024 Oklahoma Statewide Housing Needs Assessment reports findings that the greatest need is for small, affordable homes—exactly the product that existing zoning and economics make hardest to build.
- About 41% of Oklahomans are cost‑burdened, and rural lawmakers highlighted lack of workforce housing as a key deterrent to attracting employers to faltering communities.
- Building activity is heavily concentrated: Oklahoma and Tulsa counties plus nearby Cleveland County account for about 90% of building permits over the past decade; some rural counties (e.g., Beaver County) saw only nine permits since 2010.
Patterns in rural Oklahoma
- Exclusionary single‑family zoning dominates even in many smaller cities, limiting duplexes, small multifamily, and “missing middle” formats that could serve workforce households.
- Many rural counties face population decline, aging housing that needs replacement, and too little new construction to maintain, let alone grow, the stock.
- The state has responded with the Oklahoma Housing Stability Program, channeling hundreds of millions of dollars into low‑interest loans for builders, but early feedback notes that platting and infrastructure costs in rural areas remain a major barrier.
Trajectory for rural Oklahoma
Without ongoing state support and local capacity building, most rural counties will stay in low‑construction mode: small numbers of single‑family builds, slow replacement of obsolete stock, and persistent workforce‑housing shortages. Where local governments can loosen zoning for small homes and missing‑middle units, state builder‑loan programs could slowly seed more modest single‑family and small rental projects.
Rural Texas: higher growth pressures, but very uneven
Texas has some of the fastest‑growing rural‑adjacent areas in the country, but also wide swaths of stagnant or declining rural counties. State workforce and regional plans (Panhandle and Permian) highlight that strong job growth in energy, food processing, logistics, and healthcare is colliding with limited local housing and infrastructure in many rural counties.
The Texas Workforce Commission projects continued growth in construction employment to 2032, reflecting ongoing demand for housing and infrastructure across the state. Panhandle and Permian Basin workforce plans explicitly note the need for “more housing and better‑quality housing” as a condition of sustainable regional growth.
Patterns in rural Texas
- Rural and micropolitan Texas includes fast‑growing exurban rings around metros (Dallas–Fort Worth, Austin, San Antonio, Houston) and along freight corridors with strong single‑family subdivision activity.
- Energy‑ and meat‑processing‑driven hubs in the Panhandle and West Texas face workforce housing pressure and limited modern rentals.
- More remote counties continue to experience declining or flat populations and aging housing stock.
- In growth areas, new construction is dominated by single‑family detached homes and manufactured housing; purpose‑built multifamily and townhomes are relatively scarce outside small metros. Many rural regions struggle to attract builders and skilled construction labor, similar to Oklahoma, which slows the response even when demand is strong.
Trajectory for rural Texas
Along high‑growth corridors (Panhandle meatpacking/food processing, Permian Basin energy, I‑35 and I‑45 exurban counties), housing demand will likely remain strong or increase, keeping pressure on workforce rentals and modest ownership units. If construction capacity keeps expanding, these areas could gradually add significant single‑family and some small multifamily, but local infrastructure (water, sewer, broadband) and permitting will be decisive bottlenecks.
More remote ranching and agricultural counties may continue to see little building and incremental deterioration, echoing high‑poverty Southern patterns rather than high‑growth Southwest patterns.
Targeted patterns and likely trajectories for rural Texas and Oklahoma
Shared themes
- Both states face workforce‑housing shortages in many rural areas: employers struggle to recruit because small, energy‑efficient rentals and smaller, attainable homes are scarce.
- New housing in rural zones, when it happens, often targets higher price points or larger homes, leaving gaps for households at 80–120% of area median income (classic workforce band).
- Infrastructure and development costs (plats, roads, utilities) plus lack of builders and trades constrain growth, even when loans or incentives are available.
Distinctive trajectories
Texas is likely to see:
- Continued strong rural‑adjacent and corridor growth, keeping pressure on workforce housing in Panhandle, Permian, and exurban counties;
- Gradual but uneven increases in construction, largely single‑family, with spotty experimentation in small multifamily near job hubs;
- Ongoing divergence between high‑growth small‑town regions and stagnant rural counties with aging stock.
Oklahoma is likely to see:
- Concentration of most new building in metro counties, with rural areas heavily dependent on state programs like the Housing Stability Program to jump‑start production.
- Zoning and code reform as a critical swing factor: without it, the need for small homes and missing‑middle rentals will remain largely unmet in rural communities.
- Persistent challenges in very rural counties where population decline and limited builder capacity make even modest new construction difficult.
The Rural South
First off, I admit I have very little experience in the rural South. From what I read, it seems rural housing in the South is under clear strain similar to—yet unique from—other regions. Many communities see strong or renewed demand (jobs, in‑migration, some remote workers) but have thin, aging stock dominated by single‑family and manufactured homes, plus limited new multifamily or rentals for local workers.
National analysis finds the South has the largest housing shortfall in absolute numbers (about 1.15 million homes), but—because it’s building the most—it is also the region where the gap could be closed fastest if current construction trends hold. Rural and small‑town areas across the South report that housing shortages now directly hinder employer recruitment (healthcare, manufacturing, logistics, tourism), pushing states to create dedicated rural workforce‑housing programs.
At the same time, many rural Southern regions (especially in Appalachia and parts of Alabama, Mississippi, and the Black Belt) are marked by aging, low‑quality housing, heavy reliance on manufactured homes, and high cost burdens for very low‑income residents.
Supply and product mix
- Rural Southern housing stock leans heavily toward single‑family detached homes (site‑built and manufactured); manufactured homes make up more than 20% of the stock in much of Central Appalachia and Appalachian Alabama.
- Older mobile and manufactured homes in these regions often have low property values, high energy usage, and high vacancy rates, reflecting poor quality and making them costly for residents despite low purchase prices.
- New construction in rural Southern counties tends to be modest in volume and focused on larger, higher‑end homes or subdivisions that “pencil” for builders, leaving gaps at lower price points and for small rentals.
Demand segments in rural Southern states
Workforce housing (the dominant pressure)
- Rural employers, especially hospitals, schools, manufacturers, and distribution centers, increasingly cite housing as a barrier to hiring; some health systems and local governments have begun sponsoring or co‑developing small townhome or rental projects for staff.
- Georgia’s Rural Workforce Housing Initiative, funded with about 35.7 million dollars, is one example: it specifically targets rural housing development so workers can live in the communities where new jobs are being created.
- Because many rural Southern workers have low to moderate incomes, the main demand is for modest, energy‑efficient rentals and starter homes—units that are often missing in both existing stock and new construction pipelines.
Remote‑work and amenity‑driven demand
- Some rural areas in the South—particularly near mountains, lakes, or coasts—have benefited from the broader “rural renaissance” trend, with in‑migration from higher‑cost metros and some remote workers seeking lower costs and more space.
- Investors and second‑home buyers are active in selected “hidden growth” markets (e.g., certain Sun Belt small metros and exurban counties), adding pressure where new deliveries are still relatively limited
- Even in these growth pockets, supply of quality rentals and small multifamily is thin; new units skew to for‑sale single‑family, leaving service workers and renters with few options.
Poverty, aging stock, and manufactured housing in Appalachia and the Deep South
- Research on Central Appalachia and Appalachian Alabama underscores that many households in older mobile homes face severe financial burdens, with more than 70,000 households paying over 30% of income just for utilities, due to poor energy performance.
- Manufactured housing is a crucial tenure form but is highly vulnerable to storm and flood damage, a growing concern in low‑lying and riverine parts of the rural South.
- Crowding is less pervasive than in some Western areas, but low incomes plus poor housing quality and high utility costs create a different type of housing stress.
How supply and demand are interacting
- The South builds more new housing than any other region, and rural/exurban areas capture a significant share of that growth, yet the regional gap remains large because job and population growth are also strong.
- Up for Growth’s 2024 report notes that roughly three‑quarters of rural residents nationally say there is a housing shortage and that more homes and rentals are needed, reflecting lived experience in rural Southern communities.
- Where new multifamily or townhome projects do happen in rural or micropolitan Southern markets, even relatively small deliveries can temporarily raise vacancies, but underlying demand from cost‑burdened renters and new workers usually fills them quickly.
Likely future trajectories in the rural South
1. Growth corridors and “hidden growth” markets
Rural and small‑metro counties along major freight, auto, and battery‑plant corridors (e.g., parts of Georgia, Alabama, Tennessee, the Carolinas, Texas, and Florida’s interior) will see continued job growth and in‑migration, keeping housing demand strong. If current construction levels persist, some of these areas could gradually move toward better balance—especially where states back workforce housing and local zoning allows more diverse housing types. However, without deliberate support for smaller rentals and missing‑middle formats, shortages will remain most acute at workforce price points rather than at the higher end.
2. Persistent distress in high‑poverty rural regions
Central Appalachia, the Black Belt, and other high‑poverty rural areas are likely to continue facing under‑investment, with modest or declining populations but heavy needs for replacement and rehab of substandard homes. Manufactured housing will remain critical, but replacing old, energy‑inefficient units with modern, resilient models will be central to improving affordability and reducing utility burdens. Without new public financing or regional development strategies, these areas may remain stuck in a cycle of poor housing quality, high relative costs, and limited new construction.
3. Health‑care and employer‑driven housing initiatives
Expect more hospital systems, schools, and major employers in rural Southern towns to experiment with housing—master‑leasing units, co‑developing townhomes, or advocating for zoning and infrastructure upgrades—to attract and retain staff. Successful pilots (such as employer‑linked townhome developments reserved for workers up to a certain income level) could become templates replicated across the region.
Overall, rural Southern housing is moving toward a sharper divide: dynamic growth corridors where housing construction is high but still chasing demand—especially for workforce rentals—and distressed areas where population is flat but the central challenge is replacing aging, inefficient stock and making basic housing genuinely affordable to very low‑income residents.
A note on Puerto Rico
Puerto Rico is one of the most urbanized places in the United States, and is dealing with a deep affordability crisis, suburban sprawl, and a shortage of adequate, resilient housing. Only about 6% of the territory’s residents live outside urban areas.
The East Coast
While I tend to think of the megapolitan sprawl of the Boston-New York-Philadelphia-Washington conurbation dominating the East Coast of the US, you don’t have to go too far to get out of the big city into rural America. Rural housing in the Eastern US is pulled between two forces: a “rural revival” in high‑amenity and commuter‑belt areas driven by remote workers and second‑home buyers, and deep, long‑running housing distress in parts of Appalachia and other high‑poverty regions.
As I mentioned earlier, rural counties in the Northeast have seen some of the fastest price growth in the country since 2020. Fannie Mae and other researchers note that rural demand increases since the pandemic are strongest in counties near metros, with lower densities and smaller urban populations—exactly the rural‑adjacent and vacation counties that have seen the largest increases in housing costs.
Rural “winners”: vacation and remote‑work destinations
The rural housing market remains strong in parts of New England, but also in the Catskills and Hudson Valley, parts of upstate New York; and coastal or near‑coastal towns in the Mid‑Atlantic.
Key patterns:
- Vacation counties (20%+ of stock seasonal/occasional) in the Northeast had home‑price gains near 50.9% from 2020–2023, far above pre‑pandemic trends and above non‑vacation rural counties.
- Remote‑work migrants have turned some “weekender” markets into full‑time communities. Litchfield County, Connecticut, is one example where second‑home demand morphed into primary‑residence demand among telecommuters.
- New demand skews to single‑family homes (farmhouses, lake houses, wooded lots) that can serve as both lifestyle properties and full‑time residences, so construction and renovation focus there rather than on multifamily rentals.
Likely trajectory for these areas:
- Continued elevated demand from remote workers and higher‑income in‑migrants, especially if remote/hybrid work remains durable.
- Price levels likely to stay high relative to local incomes; modest new construction and conversions (e.g., farmhouses, modular infill) will help but not fully offset demand.
- Growing local pressure to regulate short‑term rentals and protect workforce housing, as some investors convert units to STRs in popular towns and resort areas.
Rural “strugglers”: Appalachia and distressed interiors
Alongside the boom pockets, much of rural Appalachia and some interior East Coast regions face an older, more structural housing crisis.
Key patterns:
- Central Appalachia and adjacent Appalachian regions (including parts of upstate New York, Pennsylvania, West Virginia, Kentucky, Tennessee, North Carolina) have large stocks of older homes; many date from before 1930 and require repairs that owners may not be able to afford.
- A recent Central Appalachia assessment stresses that housing need is especially acute for households below 80% of area median income, and that large numbers of homes sit “one big repair away” from being uninhabitable.
- Rural homelessness has spiked in some Appalachian areas; for example, Northeast Tennessee reported a 37% rise in homelessness in 2025, linked to aging housing, disasters, and outside investors buying units for short‑term use.
Quality and infrastructure issues:
- Housing units in Appalachian Ohio (the interface between East and Midwest) are more likely than the state average to have incomplete plumbing or kitchen facilities, indicating basic habitability gaps.
- Many homes suffer from unsafe wiring, failing roofs, and mold, raising health risks and pushing some residents into cars, campers, or informal arrangements.
- New affordable construction lags far behind need, due to financing barriers, zoning, and weak local tax bases.
Likely trajectory for these areas:
- Without major new investment and policy change, many communities will see continued housing deterioration, rising homelessness or doubling‑up, and limited new construction.
- Targeted strategies—repair programs, weatherization, manufactured‑home replacement, community land trusts, zoning reform—are emerging as priorities in research, but implementation is uneven so far.
How supply and demand are responding to housing pressures across rural East Coast
Housing demand from remote workers and higher‑income in‑migrants continues to impact high‑amenity counties within a few hours of major metros, with good connectivity and schools. Local workers (teachers, healthcare staff, service workers) in those same counties face rising costs and limited rental options because much of the stock is owner‑occupied or tied up in second‑home/STR use.
In distressed Appalachian areas, demand is driven mainly by low‑income households needing safe, basic housing, plus some out‑migration reducing headline demand but not eliminating the need to replace unlivable units.
In both “revival” and “distress” areas, new rural housing supply remains dominated by single‑family homes; missing‑middle formats (duplexes, small multifamily, mixed‑use buildings in village centers) are still limited but are where many planners see opportunity. In remote‑work destinations, construction and renovation often chase higher‑end buyers: renovated farmhouses, new custom or modular homes, and vacation‑suitable properties.
In distressed counties, the main “supply” challenge is replacement and rehab—keeping older homes habitable and upgrading plumbing, wiring, roofs, and energy performance—rather than adding large numbers of new units.
Likely 5–10‑year trajectories for the rural East Coast
Rural housing markets in Northeastern and Eastern states should continue to bifurcate:
1. High‑amenity, rural‑adjacent, and vacation counties
- Continued population and price growth, anchored by remote work and second‑home demand.
- Incremental increases in supply—mostly single‑family and some small multifamily or modular projects—but likely not enough to restore pre‑pandemic affordability for local workers.
- More local debates over STR caps, zoning for accessory units and middle housing, and infrastructure upgrades to support modest densification.
2. Distressed Appalachian and high‑poverty rural interiors
- Limited net new construction, continued aging of stock, and rising need for repair, replacement, and weatherization.
- Policy and philanthropic focus on deep affordability (below 80% AMI) and on keeping older homes from slipping into uninhabitability.
- Risk of further homelessness and displacement where disasters hit or where outside investment shifts stock into short‑term or seasonal use.
3. Cross‑cutting “rural revival” corridors
- Some small towns and rural centers (particularly in New England and parts of upstate NY and PA) will keep attracting remote workers and investors, prompting modest new building and downtown mixed‑use rehabs.
- Their trajectory will hinge on broadband, local governance, and the ability to add diverse housing types; areas that do this well could become long‑term “new small cities,” while others may remain expensive but supply‑constrained weekend communities.
A Rural Housing Map
Taken together, these regional stories sketch a rural housing map that is anything but uniform. Some regions—like the Canadian Prairie Provinces and scarce US growth corridors—are cautiously closing the gap between new homes and new households. Vast regions from rural Alaska to Central Appalachia to Atlantic Canada, continue grappling with deep, persistent shortfalls in both quantity and quality of the housing supply.
In between are the “quiet boom” places where remote work, tourism, and spillover demand are reshaping markets faster than policy and construction can adjust. The through‑line is clear: unless rural communities pair smarter land‑use decisions and targeted investment with sustained building and rehabilitation, the current mix of tight winners and struggling stragglers is likely to harden into a more permanent geography of rural housing haves and have‑nots.
A Patchwork Rural Housing Supply
Thank you for reading along on this long read on housing supply in the US and Canada. The picture that emerges is less a single “housing crisis” than a patchwork of local supply stories stitched together across the continent. Some places are finally starting to close the gap between new homes and new households; others are still coasting on aging stock and wishful thinking, hoping yesterday’s houses will somehow fit tomorrow’s population.
This post continued our February theme exploring demographic trends around the world, especially in rural areas. Last week, we discussed housing trends including broad drivers of the emerging crisis in housing affordability in both developed and emerging nations. This week I wanted to focus on the quantity of housing supply in North America and how well the market is meeting the needs of a changing population.
(Note: Yes, I know Mexico is part of North America. Mexico City is the very largest urban center on the continent. Los Estados Unidos Mexicanos is an amazing nation with a long history which includes a huge chunk of what is now the Southwestern US from Texas to California. Modern Mexico is also built on the legacy and heritage of Spain, whereas the American and Canadian nations are built (mostly) on the common law of Great Britain peppered with all sorts of influences from all over. It deserves its own treatment another day.)
My bias as a planner is to see opportunity here: room for better codes, smarter infrastructure, and public‑private experiments that help rural communities and small metros build (and rehab) the housing they actually need. I didn’t get into many of the external stressors of housing supply—the unpredictable US tariffs on Canadian lumber, or the rising costs of everything else that goes into building a home. Either way, if we want a different map ten years from now—fewer overcrowded bedrooms, more lights on in the winter—we’ll have to treat housing supply as slow, intentional work, not just a backdrop to the latest headline about interest rates.
Next in this Series on Demographics and Housing in Planning
I intended to dedicate the second half of this post to housing commentaries on land use and housing investment by the likes of my friend Charles Marohn (Strong Towns) and Daniel Parolek (Missing Middle Housing). As I’ve already likely exhausted your limited weekly appetite with this longer than usual long-read, we’ll start our next post off on this theme. Then we’ll discuss some of the recent public policy initiatives to address housing affordability and supply.
I am also preparing to do my first ever webinar. Rural-Ready Engagement: Practical Tools for Small Town Planners, based on my January series of posts on community engagement here on JCShepard.com. Sign up and tune in Wed 2.25.26 Noon Mountain Time. Register on Eventbrite.
Read More
Books
Escaping the Housing Trap: The Strong Towns Response to the Housing Crisis by Charles L. Marohn, Jr. and Daniel Herriges (Wiley, 2024)
Fragile Neighborhoods: Repairing American Society, One Zip Code at a Time by Seth D. Kaplan (Little, Brown Spark, 2023)
Arbitrary Lines: How Zoning Broke the American City and How to Fix It by M. Nolan Gray (Island Press, 2022)
Missing Middle Housing: Thinking Big and Building Small to Respond to Today’s Housing Crisis by Daniel Parolek (Island Press, 2020)
Rural Housing and Economic Development (Routledge Advances in Regional Economics, Science and Policy) by Don Albrecht et al ed. (Routledge, 2017)
Studies and Reports
“Housing Affordability and Housing Demand” by Louie, Mondragon, Najjar, and Wieland, FRBSF Economic Letter 2026-03, 2 February 2026
“Housing Availability and Quality in Nebraska” by Josie Gatti Schafer and Tara Grell, University of Nebraska at Omaha, 2023.
“Homes on the Range: A Series on Housing Demand, Underproduction, and a Call for Action to Meet Housing Needs in the West to 2030” by Arthur C. Nelson, Ph.D., FAICP, The Western Planner, 2022
Resources
OECD Housing website: https://www.oecd.org/en/topics/policy-issues/housing.html
USDA Rural Development—Rural Housing Service: https://www.rd.usda.gov/about-rd/agencies/rural-housing-service
USDA Economic Research Service (ERS)—Rural Economy & Population: https://www.ers.usda.gov/topics/rural-economy-population
US HUD Exchange—Rural Gateway: https://www.hudexchange.info/programs/rural/
Housing Assistance Council (HAC) Research and Information: https://ruralhome.org/information-center/rural-research-guides
Rural Community Assistance Corporation (RCAC) Housing Resources: https://www.rcac.org/housing
More from JCShepard.com
2026: Bring Your Plans to Life – Monthly Themes Preview
- Reviving Rural America: Why Heritage Tourism Is a Game-Changer Now (September 2025)
- How Small Towns Succeed: A Proven Playbook for Rural Action (November 2025)
- The Rural Comeback: How Small Town Innovation Sparks Growth (August 2025)
- How Small Towns Can Build a Strong Outdoor Economy Without Selling Out (June 2025)
Check out The 12 Planning & Sustainability Books You Need in 2026 and browse through the Small Town & Rural Community guides on our Resources page.
(As an Amazon Associate, we may earn commissions from qualifying purchases. Check your local library or bookshop, too.)
..